
Dividend Snapshot – Triton Valves Limited
Triton Valves Limited (BSE: 505978), India’s largest tyre-valve manufacturer, declared a final dividend of ₹2.50 per share for FY26 — a headline 25% on the ₹10 face value. But at the current market price of about ₹1,093, the real cash yield is only 0.23%. Importantly, the drop from last year’s ₹10 is not a dividend cut — the company issued a 3:1 bonus in April 2026, so on a like-for-like basis the payout is flat.
Dividend Per Share
₹2.50
Dividend Type
Final (FY26)
Face Value
₹10
Real Dividend Yield (at CMP)
0.23%
Record Date
18 September 2026
Total Dividend Outflow
₹1.28 Crore
Company Overview – Triton Valves Limited
Incorporated in 1975 and part of the Triton Group, Triton Valves Limited is described as India’s largest manufacturer of valves and valve cores for the tyre and tube industry, supplying tyre, tube and original-equipment makers. The company has diversified beyond automotive valves into climate-control components and brass metals, and serves sectors spanning air-conditioning, hydraulics, aerospace, mining and defence. It is a BSE-listed small-cap (market capitalisation around ₹560 Crore) with roughly 6,600 shareholders. Consolidated revenue has grown from ₹214 Crore in FY20 to ₹578 Crore in FY26, a five-year sales CAGR near 20%, though margins remain thin and the balance sheet carries meaningful debt.
Triton Valves Limited Financial Analysis
On a consolidated basis, Triton Valves grew FY26 revenue to ₹578 Crore (up ~18%) with operating profit of ₹40 Crore and net profit of about ₹10 Crore (EPS ₹18.96). Operating margins are structurally low at roughly 7%, and interest cost of about ₹13 Crore absorbs a large share of operating profit. A key caveat: the trailing-twelve-month profit of ₹18 Crore is flattered by a one-time ~₹4.75 Crore merger-related tax credit booked in the June 2026 quarter — stripping that out, normalised earnings are closer to ₹13 Crore.
| Consolidated (₹ Cr) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 428 | 488 | 578 |
| Operating Profit | 31 | 31 | 40 |
| Net Profit | 3 | 5 | 10 |
| EPS (₹, bonus-adj.) | 5.98 | 10.67 | 18.96 |
Source: Screener.in consolidated financials.
Triton Valves Limited Dividend History
The nominal per-share dividend looks volatile, but the picture changes once the 3:1 bonus (April 2026) is applied. Restating earlier payouts to the current, bonus-expanded share base shows the dividend has effectively been flat at ₹2.50 for three years running.
| Financial Year | Nominal DPS | % on FV | Bonus-Adjusted DPS |
|---|---|---|---|
| FY21 | ₹20.00 | 200% | ₹5.00 |
| FY22 | ₹5.00 | 50% | ₹1.25 |
| FY23 | Nil | — | Nil (loss year) |
| FY24 | ₹10.00 | 100% | ₹2.50 |
| FY25 | ₹10.00 | 100% | ₹2.50 |
| FY26 | ₹2.50 | 25% | ₹2.50 |
Bonus-adjusted figures divide pre-bonus DPS by 4 (3:1 bonus). Sources: BSE corporate actions, Screener.in.
Expert Commentary on Triton Valves Limited Dividend
The single most misread fact here is the headline. A casual reader sees ₹10 last year versus ₹2.50 now and assumes a 75% dividend cut. In reality, a shareholder who held one share in FY25 now holds four after the 3:1 bonus, so four shares × ₹2.50 = ₹10 of cash — identical to last year. The total company outflow is also unchanged at about ₹1.28 Crore. The more useful observation is that Triton Valves is a low-payout, growth-retention company, not an income stock: it retains roughly 87% of profits to fund capex, working capital and debt servicing. The dividend is a token of consistency rather than a meaningful yield.
Triton Valves Limited Dividend Outlook
Triton Valves has maintained a steady bonus-adjusted payout of ₹2.50 across FY24–FY26, suggesting the board is comfortable holding the absolute outflow near ₹1.3 Crore while directing surplus into growth. The company is pursuing an amalgamation/merger (NCLT process in 2026) and expanding into higher-value TPMS valves, climate-control and metals. Management has guided to strong top-line momentum, with Q1 FY27 revenue up sharply year-on-year. For dividends, the realistic expectation is continuity rather than growth: as long as earnings and cash flows hold, a similar token payout is plausible, but investors should not assume rising distributions while debt reduction and capex remain priorities. All forward statements depend on disclosed company guidance.
Triton Valves Limited Dividend Announcement Summary
Alongside its audited FY26 results on 28 May 2026, the Board of Triton Valves Limited recommended a final dividend of ₹2.50 per equity share (25% of the ₹10 face value) for the year ended 31 March 2026, subject to member approval. Shareholders approved the dividend at the 50th Annual General Meeting held on 25 September 2026. The record date was 18 September 2026 to determine eligible shareholders. This was the first cash dividend declared after the 3:1 bonus issue, which is why the per-share figure is one-fourth of the prior year’s nominal ₹10 while the economic payout to continuing holders is unchanged.
Triton Valves Limited Key Dates Timeline
Announcement Date
28 May 2026
Record Date
18 September 2026
Ex-Dividend Date
18 September 2026
AGM (Approval)
25 September 2026
Payment Date
Not Disclosed by Company
Statutory Payment Window
Within 30 days of AGM
Ex-date and record date are reported as the same day by market data sources; investors should confirm the exact payment date against the official BSE corporate-action circular and the company’s AGM outcome filing.
Triton Valves Limited Dividend Yield Analysis
This is where headline numbers mislead most. The “25%” figure is calculated on the ₹10 face value, not on the market price. Measured against the actual share price, the yield is tiny.
Headline Yield (on face value)
25.0%
Real Yield (at CMP ₹1,093)
0.23%
Yield at Announcement (₹992)
0.25%
Headline-vs-Real Gap
~109x
In plain terms: for every ₹1,093 invested, the cash dividend is about ₹2.50 a year. Triton Valves is clearly not a dividend-yield play.
Triton Valves Limited Dividend History Analysis
Classified by behaviour, Triton Valves is a cyclical / irregular payer rather than a steady compounder of distributions. It paid generously in profitable years (₹20 in FY21), skipped FY23 during a loss, and resumed at a bonus-adjusted ₹2.50 from FY24. The encouraging reading is that once earnings recovered, the board reinstated and held the payout at a stable bonus-adjusted level for three consecutive years. The cautious reading is that the dividend has tracked profitability closely and was suspended under stress — so it should be viewed as earnings-dependent and discretionary, not a guaranteed annual income stream. The absolute cash committed remains modest at about ₹1.3 Crore a year.
Triton Valves Limited Financial Performance Analysis
The operating-leverage story is improving but fragile. Over FY24–FY26, revenue rose from ₹428 Cr to ₹578 Cr (+35%) while operating profit climbed from ₹31 Cr to ₹40 Cr (+29%) and net profit from ₹3 Cr to ₹10 Cr. Margins expanded only modestly because the business is high-volume, low-margin (OPM ~7%) and heavily affected by raw-material (brass) costs and interest expense of ~₹13 Cr. Profit growth optically looks explosive (TTM up ~285%), but a large part is base effect plus the one-time ₹4.75 Cr tax credit. Underlying profitability — ROE around 9% (three-year average just 6%) — remains below the company’s cost of capital.
Triton Valves Limited Cash Flow Analysis
Reported profit is only part of the story; cash tells the rest. Triton Valves’ operating cash flow is volatile: it swung from ₹25 Cr (FY24) to negative ₹14 Cr (FY25) and back to ₹18 Cr (FY26), largely driven by a long cash-conversion cycle (~106 days) and heavy inventory. Free cash flow was negative ₹29 Cr in FY25 before recovering to ₹4 Cr in FY26.
| Consolidated (₹ Cr) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Operating Cash Flow | 25 | -14 | 18 |
| Free Cash Flow | 21 | -29 | 4 |
| Dividend Outflow | ~1.3 | ~1.3 | ~1.3 |
The good news: the ₹1.3 Cr dividend is tiny next to even a weak-year cash flow, so it is comfortably affordable in absolute terms.
Triton Valves Limited Balance Sheet Strength
The balance sheet is the real constraint on distributions. Against a net worth of about ₹128 Crore, Triton Valves carries borrowings of roughly ₹132 Crore and cash of only ₹3.5 Crore, leaving net debt near ₹128 Crore and a debt-to-equity of ~1.0x. CRISIL maintains a credit rating on the company (last updated October 2025). With leverage this high and cash reserves thin, capital is better deployed toward debt reduction and growth capex than large dividends — which is consistent with the low payout the board has chosen.
Borrowings
~₹132 Cr
Cash & Equivalents
~₹3.5 Cr
Net Debt
~₹128 Cr
Debt-to-Equity
~1.0x
Triton Valves Limited Dividend Sustainability Analysis
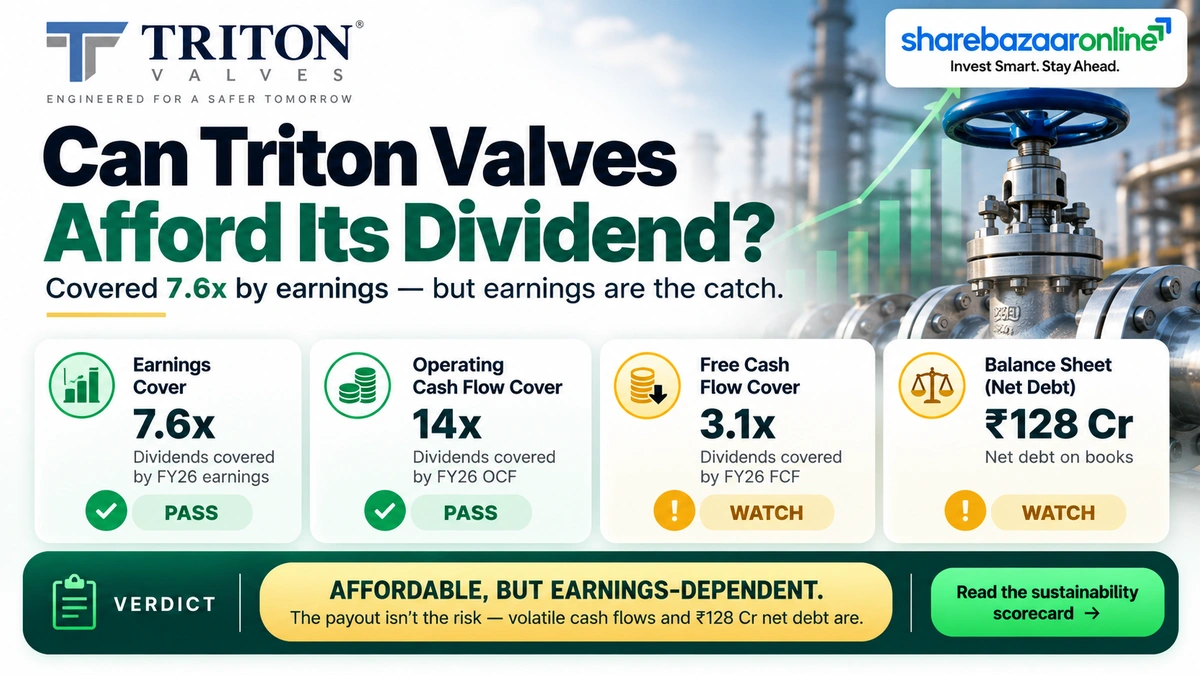
On the four-test scorecard, the small absolute payout passes comfortably on every affordability metric in a normal year — the risk is earnings volatility, not size.
| Coverage Test | Ratio | Read |
|---|---|---|
| Earnings (EPS ÷ DPS) | 7.6x | Strong |
| Operating Cash Flow | 14.1x | Strong (FY26) |
| Free Cash Flow | 3.1x | Adequate (FY26) |
| Cash Reserves | 2.8x | Thin buffer |
Verdict: Sustainable as a token payout — but it depends on earnings holding up (the dividend was skipped in the FY23 loss year), and it is immaterial for income seekers.
Triton Valves Limited Peer Comparison
Triton Valves has no listed pure-play tyre-valve peer, so it is best read against the broader auto-components space (sector P/E ~38). It screens as a low-yield, modest-return, higher-leverage name versus typical mid/large auto-ancillaries.
| Metric | Triton Valves | Auto-Component Peers (indicative) |
|---|---|---|
| Dividend Yield | ~0.23% | ~0.5% – 1.5% |
| Payout Ratio | ~13% | ~20% – 35% |
| ROE | ~9% | ~12% – 18% |
| ROCE | ~11% | ~15% – 20% |
| Debt-to-Equity | ~1.0x | ~0.1x – 0.5x |
Peer ranges are indicative sector benchmarks, not a single named company. Verify against current data before publication.
Triton Valves Limited Promoter Impact Analysis
Promoters hold 46.11% of Triton Valves (June 2026), with no FII or DII holding and the public owning the balance ~54%. On the ₹1.28 Crore total outflow, the promoter group receives about ₹59 lakh and public shareholders roughly ₹69 lakh. Because the payout is small and proportional, there is no disproportionate promoter benefit here — unlike cases where a high dividend mainly rewards a dominant promoter. One governance point worth noting: promoter holding has fallen about 6.7 percentage points over three years (from ~52.9% to ~46.1%), a trend investors may want to understand in the context of the ongoing merger and capital actions.
Triton Valves Limited Dividend Taxation Analysis
Since FY2020-21, dividends are taxable in the hands of the shareholder at their applicable income-tax slab rate. Under Section 194, an Indian company deducts 10% TDS only if total dividend to a resident individual exceeds ₹10,000 in a financial year (threshold raised from ₹5,000 from FY2025-26); without PAN, TDS is 20%. NRIs are taxed under Section 195.
| Worked Example | 1,000 shares | 5,000 shares |
|---|---|---|
| Gross Dividend (₹2.50/sh) | ₹2,500 | ₹12,500 |
| TDS (10% if > ₹10,000) | Nil | ₹1,250 |
| Tax at 30% slab | ₹750 | ₹3,750 |
| Net After-Tax Dividend | ₹1,750 | ₹8,750 |
Illustrative only; TDS is adjusted against final slab-based liability. This is general information, not tax advice.
Key Risks for Triton Valves Limited Investors
- High leverage: Net debt of ~₹128 Cr against ~₹128 Cr net worth (D/E ~1.0x) leaves limited balance-sheet cushion and heavy interest cost (~₹13 Cr/year).
- Thin, cyclical margins: OPM of ~7% is exposed to brass/raw-material price swings and auto-sector demand cycles.
- Volatile cash generation: Operating cash flow turned negative in FY25; a long ~106-day cash-conversion cycle ties up working capital.
- Earnings quality: TTM profit is flattered by a one-time ~₹4.75 Cr tax credit; normalised earnings are materially lower.
- Negligible dividend yield: At ~0.23%, the stock offers almost no income; returns depend entirely on growth and re-rating.
- Merger execution & low float liquidity: An ongoing amalgamation and thin trading volumes add uncertainty and price volatility.
What To Monitor in Triton Valves Limited
- Debt trajectory: Whether borrowings fall and interest coverage improves over the next few quarters.
- Normalised profitability: Core PAT and margins excluding one-off tax credits and merger gains.
- Operating cash flow consistency: Whether OCF stays positive and the working-capital cycle shortens.
- Merger/amalgamation outcome: NCLT approval, accounting impact and any change in share capital.
- New-product ramp: Traction in TPMS valves, EV valves, climate-control and metals segments.
- Payout policy: Whether the board lifts the bonus-adjusted dividend above ₹2.50 as earnings scale, or continues prioritising reinvestment.
Conclusion – Triton Valves Limited Dividend
Triton Valves Limited’s FY26 final dividend of ₹2.50 per share is best understood through one lens: it is a bonus-adjusted continuation of last year’s payout, not a cut, and it is economically immaterial at a ~0.23% market yield. The affordability is never in doubt — the outflow is barely ₹1.3 Crore against a company earning ₹10–13 Crore — but the balance sheet (net debt ~₹128 Cr), thin margins and lumpy cash flows explain why management keeps the payout small and reinvests the rest. For investors, Triton Valves is a growth-and-turnaround story, not a dividend-income stock. The positives are rising revenue and reinstated consistency; the negatives are leverage, earnings volatility and one-off-flattered profits. Readers should weigh these and decide for themselves.
Frequently Asked Questions About Triton Valves Limited Dividend
What dividend has Triton Valves Limited announced for FY26?
What is the dividend yield of Triton Valves Limited?
Why did the dividend fall from ₹10 to ₹2.50 — is it a cut?
What was the record date for the Triton Valves dividend?
What is the ex-dividend date?
When will the Triton Valves dividend be paid?
Who was eligible to receive the dividend?
How is the Triton Valves dividend taxed?
Is the Triton Valves dividend sustainable?
What is the dividend history of Triton Valves Limited?
Is Triton Valves a good stock for dividend income?
What should investors monitor going forward?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, tax or legal advice, or any recommendation to buy, sell or hold securities. ShareBazaar Online is not a SEBI-registered investment adviser. All figures are drawn from publicly available sources (company filings, BSE disclosures, Screener.in and market data providers) and have been reconciled to the best of our ability; some data points are marked as not disclosed or indicative and should be independently verified against official company and exchange filings before any decision. Market prices, yields and ratios change continuously. Dividend eligibility, record dates and payment timelines are subject to the company’s official corporate-action notices. Investors should conduct their own due diligence and consult a qualified financial or tax professional. ShareBazaar Online accepts no liability for any loss arising from reliance on this content.