
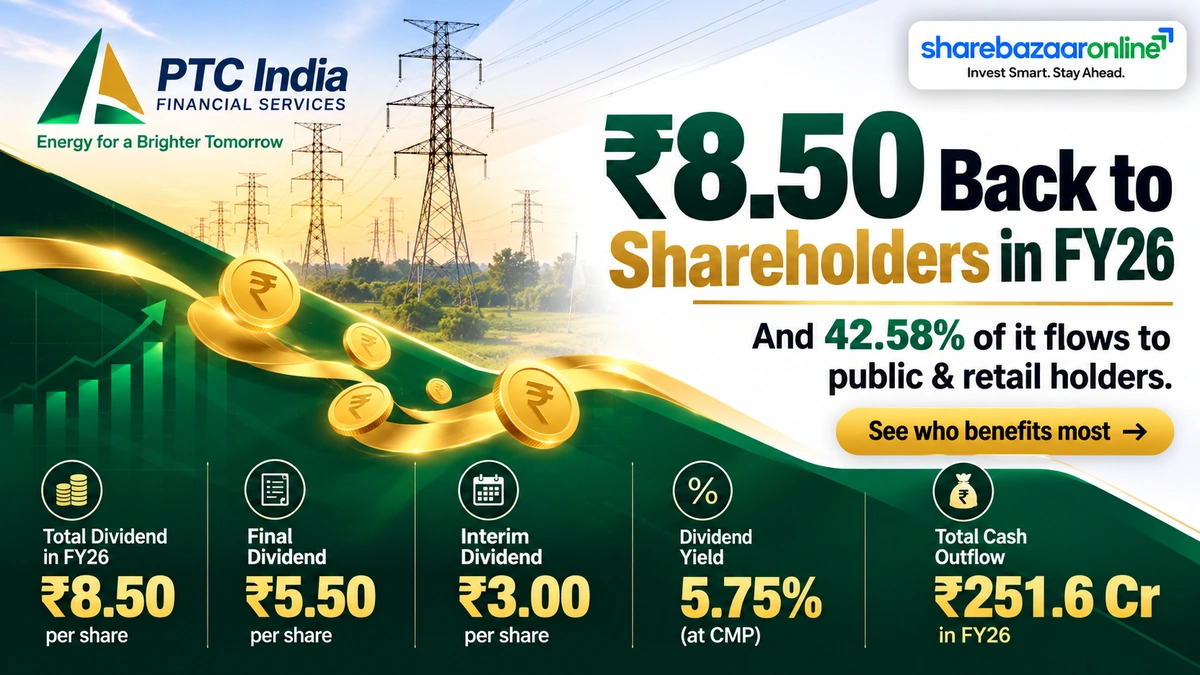
Dividend Snapshot – PTC India Limited
PTC India Limited (NSE: PTC, BSE: 532524) has declared a final dividend of ₹5.50 per share for FY2025–26, carrying a headline rate of 55% on the ₹10 face value. Taken with the ₹3.00 interim paid earlier, the full-year FY26 payout is ₹8.50 per share. The record date for the final dividend was 7 October 2026. On the current market price of ₹147.90, the final dividend translates to a real yield of about 3.72%, and the FY26 total to roughly 5.75% — a long way from the 55% figure, which is only a calculation on face value.
Dividend Details
| Dividend Type | Final (FY26) |
| Final Dividend | ₹5.50 / share |
| Headline Rate | 55% on FV ₹10 |
| FY26 Total (incl. ₹3 interim) | ₹8.50 / share |
| Record Date | 7 Oct 2026 |
Key Metrics
| Real Yield (final, on CMP) | 3.72% |
| FY26 Total Yield | 5.75% |
| Standalone EPS (FY26) | ₹13.41 |
| Consolidated Payout (FY26) | 35.1% |
| Final Dividend Outflow | ₹162.8 Cr |
Company Overview – PTC India Limited
PTC India Limited, formerly Power Trading Corporation of India, is the country’s largest power-trading company. It buys and sells electricity in the short-term market, runs bilateral and cross-border trades, and earns a thin margin on every unit traded. In FY26 (standalone) it traded 92,802 million units, up 12%, at a core trading margin of about 3.35 paise per unit. The company was promoted by four state-owned power majors — collectively holding just 16.22% — and its remaining shares sit with foreign investors (28.88%) and the public (42.58%). Its consolidated profit also reflects earnings from associate businesses, including a financial-services arm, which makes the standalone vs consolidated distinction important for any dividend reader.
PTC India Limited Financial Analysis
PTC India’s reported profit looks like it fell, but the real picture is the opposite. Consolidated profit after tax (continuing operations) was ₹717.4 Cr in FY26 versus ₹853.7 Cr in FY25 — a 16% “decline.” However, FY25 included a one-time gain of ₹241.7 Cr from the divestment of a subsidiary (PEL). Strip that out and FY25 underlying profit was about ₹612 Cr, meaning FY26 profit actually grew roughly 17%. Standalone EPS was ₹13.41; consolidated EPS works out to about ₹24.24, the gap reflecting profits contributed by associate companies. This earnings-quality nuance is routinely missed in wire-service coverage.
PTC India Limited Dividend History
Dividend per share by financial year (interim + final combined). Source: exchange filings and corporate-action records.
| Financial Year | DPS (₹) | YoY Change |
|---|---|---|
| FY18 | 4.00 | — |
| FY19 | 4.00 | 0.0% |
| FY20 | 5.50 | +37.5% |
| FY21 | 7.50 | +36.4% |
| FY22 | 7.80 | +4.0% |
| FY23 | 7.80 | 0.0% |
| FY24 | 7.80 | 0.0% |
| FY25 | 11.70 | +50.0% |
| FY26 | 8.50 | −27.4% |
| FY27 (interim so far) | 23.00 | special-scale |
8-year DPS CAGR (FY18→FY26): approximately 9.9%. The ₹23.00 FY27 interim (paid August 2026) is an exceptionally large, separate capital-return event.
Expert Commentary on PTC India Limited Dividend
The headline investors should not fixate on is “55%.” On a ₹10 face value that is simply ₹5.50, and against a market price near ₹148 the real final-dividend yield is about 3.72%. The more striking fact is the pace of capital return: within roughly two months (August and October 2026), PTC India returned ₹31.50 per share in cash — the ₹23.00 FY27 interim plus the ₹5.50 FY26 final — totalling close to ₹844 Cr. The ₹23 interim alone, at about ₹681 Cr, equalled roughly 95% of a full year’s consolidated profit. That signals a company distributing accumulated reserves and divestment cash, not merely sharing current-year earnings.
PTC India Limited Dividend Outlook
Looking forward, the recurring dividend and the one-off capital return are two different stories. The regular payout has been trimmed from ₹11.70 (FY25) to ₹8.50 (FY26), down 27%, while the large ₹23 FY27 interim appears to be a special-scale distribution rather than a new normal. PTC India’s standalone business remains cash-generative and carries minimal parent-level debt, which supports the recurring dividend. What is not disclosed is whether further large capital returns will follow, so the sustainable expectation is the recurring ₹8–₹9 range rather than the exceptional FY27 figure. Trading-margin trends and short-term power demand will shape future distribution capacity.
PTC India Limited Dividend Announcement Summary
The PTC India Limited dividend was recommended by the Board of Directors on 19 May 2026 alongside FY26 results, and is declared at the 27th Annual General Meeting held on 30 September 2026. Under SEBI (LODR) Regulation 42, the company fixed 7 October 2026 as the record date to determine which shareholders are entitled to the ₹5.50 final dividend. Because the AGM approval was required, this is a final dividend (not interim). The intimation to BSE and NSE was filed on 18 August 2026. All figures here are drawn from the company’s own exchange disclosure; the editorial commentary is separate and clearly flagged.
PTC India Limited Key Dates Timeline
| Board Recommendation | 19 May 2026 |
| Exchange Intimation (Record Date) | 18 Aug 2026 |
| 27th AGM (Declaration) | 30 Sep 2026 |
| Ex-Dividend Date | 7 Oct 2026 |
| Record Date | 7 Oct 2026 |
| Payment Date | By ~30 Oct 2026* |
*Under T+1 settlement the ex-date coincides with the record date. The payment date is not separately disclosed; the Companies Act, 2013 (Section 127) requires dividend payment within 30 days of declaration at the 30 September 2026 AGM.
PTC India Limited Dividend Yield Analysis
This is where the face-value illusion matters most. A “55% dividend” sounds enormous, but 55% is calculated on the ₹10 face value, giving just ₹5.50. What an investor actually earns depends on the market price. At the current ₹147.90, the real final-dividend yield is only about 3.72%. Adding the ₹3.00 FY26 interim lifts the full-year recurring yield to around 5.75%. The headline rate and the real yield differ by a factor of about fifteen. The FY27 ₹23 interim, if annualised, would imply a very high yield — but it is a one-off capital return, not a repeatable payment, so it should not be read as a sustainable income rate.
PTC India Limited Dividend History Analysis
PTC India qualifies as a consistent dividend payer. It has paid an uninterrupted dividend every year in the period reviewed, with no suspensions, and a steadily rising base — from ₹4.00 in FY18 to ₹8.50 in FY26, an 8-year CAGR of about 9.9%. The trend is not perfectly linear: payouts plateaued at ₹7.80 across FY22–FY24, spiked to ₹11.70 in FY25, then eased to ₹8.50 in FY26 (down 27%). The FY25 peak coincided with the subsidiary-divestment year, so part of that distribution reflected one-time cash rather than a durable step-up. Read correctly, the recurring dividend sits in the ₹8–₹9 band, with occasional special-scale top-ups such as the FY27 interim.
PTC India Limited Financial Performance Analysis
On the operating line, FY26 was a growth year, not a decline. Standalone revenue rose to about ₹16,256 Cr (from ₹15,050 Cr), traded volume climbed 12% to 92,802 MUs, and the total operating margin edged up 2% to ₹408 Cr. Consolidated continuing-operations profit grew roughly 17% once the FY25 one-time divestment gain is excluded. The apparent profit drop is therefore an accounting-base effect, not deteriorating operations. The watch-point is margin per unit: at 3.35 paise the core trading spread is thin, so profitability is sensitive to volume and to competition from power exchanges, where a growing share of trades now takes place.
PTC India Limited Cash Flow Analysis
Reported profit is an opinion; cash is a fact — and here the cash picture supports the dividend. Consolidated operating cash flow was strong in recent years (around ₹2,132 Cr in FY25, ₹2,451 Cr in FY24 and ₹3,575 Cr in FY23), comfortably exceeding the FY26 dividend outflow of about ₹251.6 Cr. However, power-trading cash flows swing widely with working capital and receivable cycles, so a single year should not be over-read. Crucially, the exceptional ₹23 FY27 interim (₹681 Cr) was far larger than one year’s recurring cash generation can fund — indicating it drew on accumulated reserves and divestment proceeds rather than operating cash alone.
PTC India Limited Balance Sheet Strength
PTC India’s balance sheet is the backbone of its distribution ability. Consolidated net worth was roughly ₹5,800 Cr (equity capital ₹296 Cr plus reserves of about ₹5,509 Cr at FY25), against a book value near ₹197 per share. The group’s reported borrowings (about ₹2,962 Cr at FY25, trending down) sit largely in the financial-services arm’s lending book — the parent power-trading entity is effectively near debt-free, reflected in a low consolidated debt-to-equity of about 0.16. This reserve cushion, boosted by divestment cash, is precisely what allowed the company to pay ₹31.50 per share across August and October 2026 without stressing the business.
PTC India Limited Dividend Sustainability Analysis
On a four-test framework, the recurring FY26 dividend screens as sustainable; the one-off FY27 interim is a reserve-funded capital return, by definition not repeatable.
- Earnings coverage: consolidated EPS ₹24.24 covers the FY26 total (₹8.50) 2.85x; standalone EPS ₹13.41 covers it 1.58x.
- Operating cash: OCF far exceeds recurring dividend outflow, though it is volatile.
- Balance sheet: near debt-free parent with a large reserve cushion.
- Earnings trend: underlying profit up ~17% in FY26 once one-offs are removed.
Verdict on the recurring dividend: Sustainable. Verdict on special-scale returns: dependent on surplus cash, not assured.
PTC India Limited Peer Comparison
| Company | Div Yield | ROE | ROCE | D/E |
|---|---|---|---|---|
| PTC India | 5.75% | 8.65% | 15.01% | 0.16 |
| SJVN | 2.71% | 4.86% | 5.59% | 1.91 |
| CESC | 4.50% | 12.29% | 11.48% | 1.22 |
| Jaiprakash Power | 0.00% | 6.93% | 6.98% | 0.23 |
Against listed power-sector peers, PTC India offers the highest recurring dividend yield (5.75%), the best ROCE (15.01%) and the lowest leverage (D/E 0.16). Its ROE is moderate, held down by the asset-light, thin-margin trading model. Figures are peer-table data as published and move with price.
PTC India Limited Promoter Impact Analysis
PTC India’s ownership makes this dividend unusually investor-friendly. With the four PSU promoters holding only 16.22%, the promoter’s share of the ₹162.8 Cr final-dividend outflow is just about ₹26.4 Cr. The largest beneficiaries are public and retail shareholders (42.58%), who collect roughly ₹69.3 Cr, followed by foreign investors (28.88%, about ₹47.0 Cr) and domestic institutions (12.32%, about ₹20.1 Cr). In most Indian companies promoters capture the majority of dividend cash; here the distribution flows overwhelmingly to minority holders. That low promoter stake, combined with a high FII presence, also helps explain the recent emphasis on aggressive capital return.
PTC India Limited Dividend Taxation Analysis
Since FY2020–21, dividends are taxed in the shareholder’s hands at their applicable income-tax slab rate. The company deducts TDS at 10% under Section 194 once total dividend from that company crosses ₹10,000 in a financial year (20% without a valid PAN; Form 15G/15H can exempt eligible investors).
Worked example — 1,000 shares at ₹8.50 (FY26 total), 30% slab:
- Gross dividend: 1,000 × ₹8.50 = ₹8,500
- TDS: not applicable (below the ₹10,000 threshold)
- Tax at 30% slab (plus cess): about ₹2,652
- Net in hand: approximately ₹5,848
- Post-tax effective yield (on ₹147.90): about 4.0%
Illustrative only; individual tax depends on total income and status. This is not tax advice.
PTC India Limited – Key Risks
- Thin trading margins: core spread of about 3.35 paise per unit leaves little buffer; small margin compression hits profit hard.
- Exchange disintermediation: a rising share of power is traded on exchanges (IEX and others), structurally pressuring the trader’s role and volumes.
- Recurring-dividend cut: the regular payout already fell 27% in FY26 (₹11.70 → ₹8.50); the big FY27 interim is one-off, not a new base.
- Counterparty and receivable risk: delayed payments from state distribution utilities can strain working capital and cash flows.
- Earnings mix: consolidated profit leans on associate contributions, so group earnings can move for reasons outside the core trading business.
PTC India Limited – What To Monitor
- Core trading margin (paise/unit): the single most important driver of recurring profit and dividend capacity.
- Traded volume growth: whether 12% FY26 growth continues as renewable and storage volumes scale.
- Future capital-return policy: any sign of a formal dividend/buyback policy after the large FY27 interim.
- Standalone cash and reserves: how much surplus remains after ₹31.50/share of recent distributions.
- Receivables cycle: trends in dues from state utilities and their effect on operating cash flow.
Should You Consider PTC India Limited for Dividend Income?
PTC India Limited presents a genuinely two-sided case. On the positive side: a consistent dividend record (8-year DPS CAGR ~9.9%), a sector-leading recurring yield of about 5.75%, the best ROCE in its peer set (15.01%), a near debt-free parent, and a distribution that flows mostly to minority shareholders. On the cautious side: the recurring dividend was cut 27% in FY26, the eye-catching ₹23 FY27 interim is a non-repeatable capital return, trading margins are structurally thin, and exchange-based trading is a long-run threat. The “55%” headline is only 3.72% in real yield terms. Investors should weigh the durable ₹8–₹9 recurring dividend separately from the one-off capital return. This is analysis, not advice.
Frequently Asked Questions About PTC India Limited Dividend
What dividend has PTC India announced?
What is the real dividend yield of PTC India?
What was the record date for the PTC India dividend?
What is the ex-dividend date for PTC India?
When will the PTC India dividend be paid?
Who was eligible for the PTC India dividend?
How is the PTC India dividend taxed?
Is the PTC India dividend sustainable?
What is the dividend history of PTC India?
Why did PTC India’s FY26 profit appear to fall?
What was the ₹23 PTC India interim dividend in August 2026?
What should PTC India dividend investors monitor?
What is the difference between PTC India’s standalone and consolidated payout?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, legal or tax advice, or any recommendation to buy, sell or hold securities. Disclosed facts are drawn from PTC India Limited’s exchange filings; market data, dividend history, shareholding and peer figures are sourced from public providers and are subject to revision. All ratios are editorial computations. ShareBazaar Online is not a SEBI-registered investment adviser. Investors should verify figures with official sources and consult a qualified professional before making any financial decision. Securities investments are subject to market risks.